Corporate tax relief UK provisions remain a cornerstone of modern financial strategy for finance directors and owner-managers navigating the complexities of the British fiscal landscape. When managing corporate finances, understanding how to legally reduce taxable profits through government-backed incentives can fundamentally alter cash flow projections. Navigating these allowances requires meticulous record-keeping and a thorough understanding of compliance standards set by authorities. Careful tax planning is never a substitute for robust commercial revenue, but it provides a reliable cushion against overhead pressures. The (Site adi belirlenmemis) team prepared this guide for you.
What is Corporate Tax Relief UK?
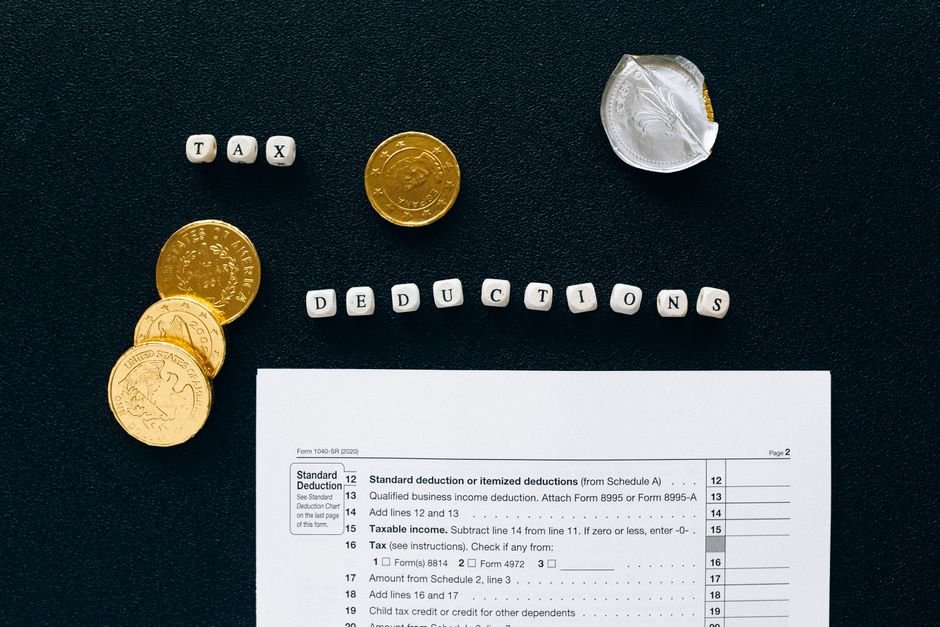
Corporate tax relief UK describes the statutory mechanisms that allow limited companies to reduce their overall Corporation Tax liability by deducting eligible expenditures or claiming specific tax credits. These reliefs are designed by policymakers to stimulate business investment, encourage scientific research, and reward capital expenditure in plant and machinery. Rather than representing guaranteed savings, these provisions are subject to rigorous verification, shifting legislative thresholds, and strict HMRC compliance checks.
Managing your company’s fiscal obligations effectively demands a structured approach to statutory deductions and exemptions. Many expanding enterprises review their uk corporation tax strategies alongside broader commercial initiatives to ensure no eligible expenditure goes unclaimed. However, finance leaders must approach every incentive with caution, recognizing that eligibility criteria change frequently and require substantiation.
Research and Development Tax Credits
Innovation sits at the heart of many growing enterprises, making research and development incentives one of the most scrutinized areas of corporate tax relief UK. According to official compliance updates, HMRC details R&D tax relief schemes to support companies that seek to resolve scientific or technological uncertainties (HMRC, 2024). Eligible entities can claim cash credits or corporation tax deductions for qualifying staff costs, software, and consumable items used directly in their qualifying projects.
Claiming these credits requires a demonstrable baseline of innovation that goes beyond standard industry practices. Companies must document their technological hurdles and experimental steps transparently to satisfy regulatory audits. As noted in guidance regarding R&D incentives, keeping contemporaneous records protects directors from clawbacks during routine compliance checks (HMRC, 2024). Prudent finance teams work closely with specialist advisers to ensure their technical narratives align precisely with statutory definitions.
Capital Allowances and Plant Deductions
Investing in physical infrastructure allows businesses to write off the cost of qualifying assets against their taxable profits through capital allowances. These mechanisms function as depreciation adjustments recognized by the tax authorities, allowing companies to deduct a proportion of asset values each year. For instance, the annual investment allowance permits complete tax relief on qualifying machinery up to specified statutory limits.
- Identify qualifying plant, machinery, and industrial buildings before financial year-ends.
- Review writing-down allowances for assets that exceed annual limits.
- Verify that asset purchases comply with current anti-avoidance legislation.
- Consult official HMRC Corporation Tax services to confirm prevailing rates and administrative procedures.
Asset management strategies must account for the timing of disposals as well as acquisitions, since selling equipment can trigger balancing charges or balancing allowances. Finance directors should model different capital expenditure scenarios to optimize the exact timing of their tax claims. A balanced approach ensures that capital investments serve both operational needs and tax efficiency goals.
Questions to Ask Your Accountant or Finance Team
Before submitting annual returns or finalizing strategic forecasts, finance directors should pose targeted questions to their internal teams and external advisers. Establishing a clear dialogue minimizes compliance risks and uncovers overlooked opportunities within the current regulatory framework. Consider raising the following inquiries during your next planning session:
“Tax relief provisions are designed to reward genuine commercial risk and investment, yet they demand absolute accuracy and robust documentation at every stage of the compliance cycle.”
Are our current research projects properly documented to withstand an HMRC enquiry? Have we maximized our capital allowances across all recent equipment purchases and facility upgrades? Do our operational workflows account for recent legislative changes regarding qualifying expenditure thresholds? Addressing these queries proactively protects the business from unexpected liabilities.
Corporate tax planning remains an evolving discipline that requires constant vigilance, ethical integrity, and close collaboration with qualified professionals. By treating tax incentives as a supplement to sound business fundamentals rather than a primary revenue source, leadership teams can build resilient organizations. For questions, contact us.
References
HMRC. R&D Tax Relief. 2024.